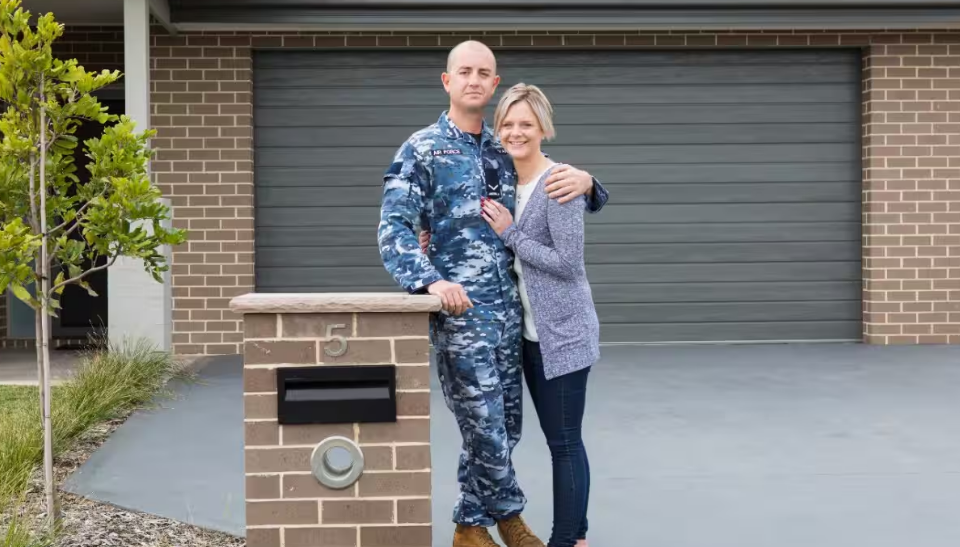
Defence Housing Australia (DHA) investment properties conjure 2 images – one of tenant security and hassle-free investing, versus that of lack of control and possible lower growth. Deciding if DHA is for you comes down to your risk profile, goals and other factors.
Long term leasing, guaranteed income and reliable tenants make up some of what makes Defence Housing a viable option for property investors.
Providing a roof overhead to some of the nation’s vital defence personnel not only sounds trustworthy, but perhaps even noble.
Like most bricks and mortar purchases, however, investing in Defence Housing Australia does come with its downsides, and investors are urged to weigh up the pros and cons before signing on the dotted line.
"An investment in knowledge pays the best interest." — Benjamin Franklin.
What is DHA?
Defence Housing Australia (DHA) is an Australian government business enterprise providing housing to members of the Australian Defence Force and their families.
Established in 1988 it boasts one of the largest property portfolios in the country (approximately 17,000 properties across Australia). Almost 12,000 (about 70%) of those are owned by independent investors in the private sector.
Responsible for the building, buying, and leasing of homes, DHA is a corporate entity delivering commercial gains (around $1 billion revenue annually) to the Australian Government.
With more than 58,000 Australians, New Zealanders, and Fijians currently serving as full-time active-duty ADF personnel, and 33,000 as ADF reservists, plus the addition of recruits from Canada, UK and USA expected from January 2025, the demand for DHA properties could rise.
Is DHA the right investment option for me?
To answer this question you must consider:
- Your risk profile
- Your personal and investment goals
- Financing the asset, and
- The pros and cons of DHA investments.
Financing your DHA investment
When considering a mortgage for a DHA property, Newcastle-based Ascension Finance Lending Specialist Joel Archer warns there are a few differences that need to be taken into account.
“While most lenders are generally open to taking DHA properties as security, they may impose specific restrictions on certain assessment criteria,” he says.
“For example, although rental income from a DHA property is guaranteed, management fees tend to be significantly higher than those associated with traditional property management.
“These higher fees are considered by lenders when assessing serviceability, potentially reducing the borrower’s overall borrowing capacity due to the increased holding costs.
“Additionally, the property's location plays a crucial role in a lender’s willingness to accept it as security.
“DHA properties in some areas, where the market may be more volatile, are sometimes viewed as higher-risk assets.
“This can lead to lenders requiring a larger deposit.”
The numbers, he says, can vary by up to 10%.
“For instance, while an investor purchasing a property in a major city or regional hub might be able to borrow up to 90% (or, in some cases, 95%) of the property’s value, lending may be restricted to 80% or less in higher-risk locations.”
How do I invest in DHA?
Traditionally there are three ways to invest in a DHA asset:
- Buying a property built by DHA and leasing it back to them for six, nine or 12 years. You can search the properties available here.
- Leasing your own investment property through DHA, or
- Buying a property that is already leased to DHA.
When buying a property from another investor that is already leased to DHA (option 3 above), investors should note they will pick up the lease that is already in place and be subject to its existing terms and conditions.
It’s worth noting, when an investor leases their property to DHA, it is being leased to the DHA organisation, not the tenant.
Pros and Cons of investing in a DHA property
The DHA acts as a service provider for the military but is also a property developer and an active purchaser of homes on the private market. In 2022-23, DHA added a total of 2,545 properties to its national portfolio, 90 of those from its own construction programs.
In fact, DHA generates most of its annual income through the sale of portions of its property portfolio to private investors, then leasing the homes back on long-term agreements.
Investment property owners considering purchasing or building a property and leasing to DHA need to be aware there are several significant differences in signing your rental property up with DHA.
They are also subject to certain guidelines.
When leasing a property to DHA, investors must register and provide specifics of the property location and its features, with DHA able to change the nature and number of properties required from time to time.
DHA will not lease an already occupied property under an existing contract with a real estate company.
Investors are advised to carefully consider whether the organisation's leasing conditions suit their own property investment goals.
Pros of a DHA investment property
Volume: To combat current declining numbers, the Australian Defence Force has opened up its recruiting to non-Australian citizens, including citizens from New Zealand and Fiji. In January 2025 it will open its doors to recruits from Canada, United Kingdom and USA which has the potential to boost the number of ADF members and families seeking DHA rental homes.
Long-term: DHA properties offer long-term lease options, with the majority of leasing agreements ranging from six to 12 years.
Guaranteed income: When signing a lease with DHA, rent is guaranteed even when the property is empty.
Continuous services: According to its Property Care Contract, DHA will continue mail collection and grounds maintenance (watering gardens, pruning trees and mowing lawns) while the property is unoccupied between tenancies.
One fee: Unlike leasing through a standard property manager, investors in DHA are charged one service fee that covers property inspections, annual rental adjustment, tenant management and property maintenance. There are no additional fees for re-letting or advertising fees when occupancy changes.
Cleaning: End of lease cleaning and appliance checks are included in the fee.
Rent: In what could be viewed as both a for and against, the rental amounts charged to tenants are determined by DHA-appointed licensed independent valuers and are based on current market rents in the area. Reviews are generally conducted annually and if landlords are unhappy with rental reviews, they can appeal them by engaging another independent valuer (at their own cost). Rent is accrued daily and paid monthly in advance for the term of the lease.
Cons of a DHA investment property
Location: DHA properties are concentrated in suburbs within 35 km of a military base. The priority locations for DHA leases can be found here.
Rental concentration can limit capital growth: DHA often enters deals with property developers, with homes purchased off the plans. These suburbs typically have a high concentration of rental properties. Whilst many factors influence capital growth, it is generally regarded that areas with more than 30% renters are not conducive to capital growth. One of the reasons behind this is that traditionally those who choose to spend the most on a home are owner occupiers, who generally prefer to live in family-friendly areas with other house-proud owners (not renters).
Restrictive rental rates: Rental rates for properties leased to DHA are based on current market rates of similar properties in the area. In the Hunter region, expected rents are currently capped at $800 per week. DHA conducts periodic market rent reviews, generally yearly, by engaging an independent licensed valuer to provide a recommendation for the rent. If investors are unhappy with a rental review, they may appeal the decision by engaging their own independent licensed valuer to conduct a valuation on your property at their own cost.
DHA leases can limit resale value: While it may initially be considered favourable, investors should consider a scenario in which they are forced to sell their property due to an unforeseen life event. In this case they may have to sell with a DHA lease in place, limiting the pool of interested buyers which can also limit resale value.
Other investors might also shy away from taking on a property already signed to a DHA lease.
Lack of control: Investors that take an active interest in their investment property may be at a loss with DHA holding most of the control, including property criteria, and maintenance. Ensuring your investment property is well maintained affords owners the reassurance it will attract good rent and returns when they eventually sell.
No bond: DHA does not pay a bond and it is up to the landlord to take out and maintain the usual insurances to cover the property.
Higher fees: DHA has higher property management fees than other managers. All DHA lease agreements include a Property Care Contract which provides a range of services for a set fee. These services include most non-structural repairs, rent reviews, and organising inspections and contractors as required. The service fee is a flat 16.5% (including GST) for most free-standing houses and 13% (including GST) where there is a body corporate responsible for common areas, including external paintwork. Standard property management fees within the private market are between 5-8%, depending on what services are provided.
*It is worth noting the cost of emergency repairs are additional to the Service Fees, and a number of repairs and responsibilities are excluded from the contract.
Suitability: DHA is quite particular on what properties are suitable for its purposes. While it leases a variety of free-standing houses, townhouses, and apartments, all must meet the organisation's minimum requirements including bedrooms with built-in wardrobes, ensuites, secure car accommodation, security screens, and climate control.
To be considered for a DHA lease, property owners must satisfy a certain criteria, including the following (accurate based on the date of original publication of this article);
- Minimum three bedrooms with built-in wardrobes
- Designated lounge, dining/meals area
- Kitchen must include a pantry
- Home must have a laundry
- Bathroom must have separate shower and bath
- Separate toilet
- Main bedroom must have an ensuite
- Double or single lock-up garage
- Property must have minimum 9 sq/m storage (if single garage)
- Three or four-bedroom homes must include a fully enclosed rear yard minimum 35m2, and
- Covered outdoor entertaining/alfresco area
Desired features include;
- Covered outdoor area, minimum 15m2 for freestanding dwellings and a minimum 10sq/m for all other dwellings
- Security screen doors and deadlocks to external doors
- Climate control to living areas and bedrooms
- Easy-care gardens
- Storage to include linen cupboard and broom cupboard
The End Game
Everyone’s situation is different so investors must always ensure their investment is aligned to the goal – to their end game.
The ultimate goal for many property investors is generally to sell, using the capital gains from the sale to fund retirement, lifestyle choices, or to reduce or remove home debt. With the long term leases in place with DHA, selling mid-lease and potentially limiting resale and capital growth is a significant disadvantage that needs factoring in to your investment decision.
So... is DHA the right investment option for you?
If you need help answering this and/or acquiring your next investment property, please get in touch with Niva Property Buyers and get started today.